Despite a rather unsettled economic and wider geo-political landscape, retail warehousing as a sector is proving to be one of the brighter lights but, as ever, the picture is nuanced and stock selection remains paramount.
New quarterly investor research from Lismore Real Estate Advisors points to limited supply and resilient demand as being the leading driver of rental growth for retail warehousing over the next few years.
Around 47% of respondents selecting limited supply as the most important factor. This was followed by asset management at 23% and convenience-led consumer spending at 20%, highlighting a combination of supply constraints, active ownership and underlying occupier demand as the key themes for rental growth.
The research highlights a preference for foodstore operators being in the tenant line-up which will be an important platform for retail warehousing performance, with 62% of respondents selecting the category. This was more than double the proportion choosing discount/value retailers (24%), while a further 14% identified drive-thru/F&B operators.
The findings varied by investor type, with foodstores selected by 75% of property company respondents and 56% of funds. Funds showed a stronger preference for discount / value retailers, at 33%, while investment managers placed greater emphasis on drive-thru/F&B operators, with 33% identifying the category compared with 12–14% across the other investor groups.
When asked about assessing retail warehousing acquisition, 34% of respondents selected dominant catchment strength as the most important acquisition characteristic, closely followed by 28% selecting asset management opportunities. A further 21% identified reversionary rental potential, with 7% selecting strong anchor tenant covenant.
For a detailed expert view on the retail warehousing sector, Lismore interviewed Gavin Munn, Senior Director at Edmond de Rothschild, who said:
“Retail warehousing continues to offer compelling fundamentals, with sustainable income, rental growth prospects and attractive relative value. Most importantly, occupational demand remains strong, with low vacancy, limited new supply and a broad range of retailers seeking space. Rents have largely rebased to affordable levels, while the continued importance of physical stores within omnichannel retailing provides further support.
Demand is also underpinned by a diverse range of sectors, including discount and value retail, food, DIY, furniture and pets. For investors, however, selectivity remains critical. The focus should be on supply-constrained micro-markets, affordable rents and assets with strong occupational demand. Well-located schemes can also offer longer-term flexibility through extensions, reconfiguration or alternative uses, adding to their investment appeal.”
Simon Cusiter, Director at Lismore concludes:
“While there is no denying that the more general retailing backdrop remains challenging, the out-of-town market looks well placed to navigate the choppy waters. The sector’s tenant demand is increasingly concentrated in those categories that remain relatively well-positioned: value, convenience, discount food, trade-led retail and essential spend.
“This kind of positive occupational story is giving investors comfort and the retail warehousing sector remains one with the deepest pool of active buyers.”
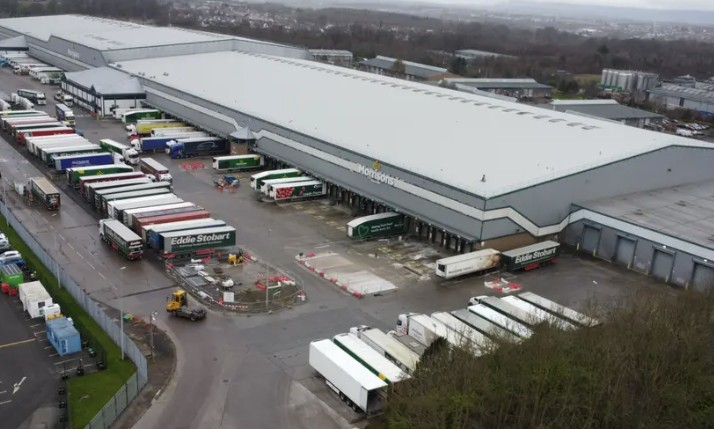
Lismore’s review also features the latest quarterly statistics, which show total investment transactions of £348 million in Q3 2026, taking the year-to-date total to £1.07bn. The largest deal of the quarter was Realty Income’s £72 million funding of the 350,000 sq ft Orchard Park scheme at Eurocentral, acquired from vendor Newlands Developments. Other notable transactions included Blacksand’s £45 million acquisition of the Morrisons Distribution Centre in Bellshill from ICG and Greenridge Investment Management acquisition of Bridgewater Shopping Centre in Erskine for £21 million from Broadland Properties.